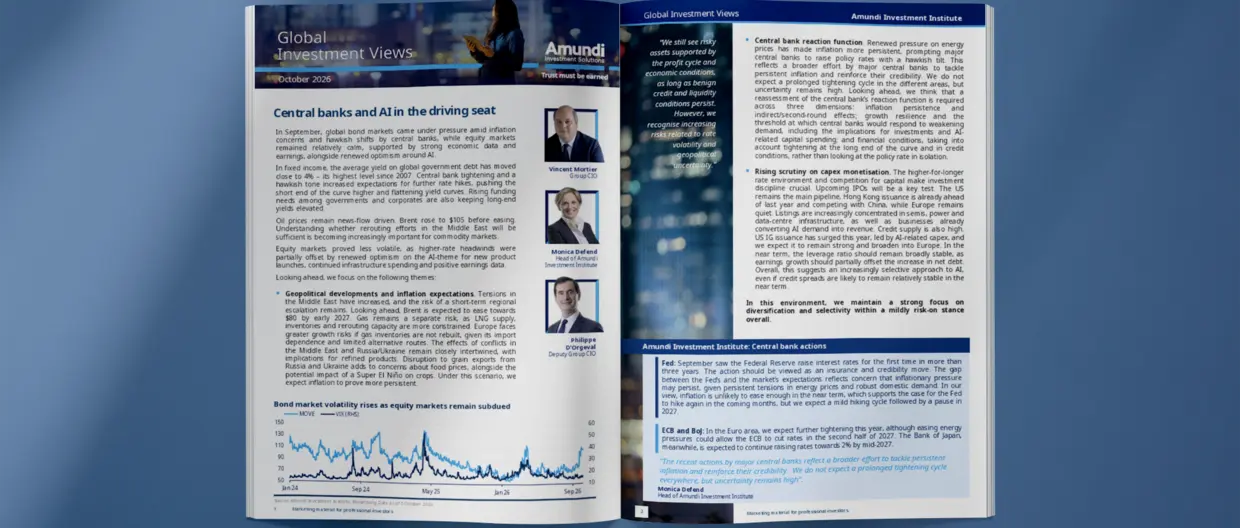
Central banks and AI in the driving seat
In September, global bond markets came under pressure amid inflation concerns and hawkish shifts by central banks, while equity markets remained relatively calm, supported by strong economic data and earnings, alongside renewed optimism around AI.
In fixed income, the average yield on global government debt has moved close to 4%, its highest level since 2007. Central bank tightening and a hawkish tone increased expectations for further rate hikes, pushing the short end of the curve higher and flattening yield curves. Rising funding needs among governments and corporates are also keeping long-end yields elevated.
Oil prices remain news-flow driven, with Brent rising to $105 before easing. Understanding whether rerouting efforts in the Middle East will be sufficient is becoming increasingly important for commodity markets.
Equity markets proved less volatile, as higher-rate headwinds were partially offset by renewed optimism on the AI theme, supported by new product launches, continued infrastructure spending and positive earnings data.
Looking ahead, we focus on the following themes:
- Geopolitical developments and inflation expectations. Tensions in the Middle East remain elevated, and inflation could prove more persistent if energy, gas and food supply risks stay high.
- Central bank reaction function. Central banks are keeping a hawkish bias to preserve credibility, while investors are reassessing how higher-for-longer rates affect growth, investment and AI-related capex.
Rising scrutiny on capex monetisation. The market is becoming more selective on AI, with greater scrutiny on IPOs, funding needs and the ability to turn capex into revenue.
In this environment, we maintain a strong focus on diversification and selectivity within a mildly risk-on stance overall.
Below we have outlined our views on asset classes in our current base-case scenario:
- In fixed income, we remain close to neutral on US duration, constructive on EMU duration with a preference for peripherals, mildly positive on UK duration, and neutral on Japan. In credit, we remain mildly constructive, with a preference for Global IG.
- In equities, we stay cautious on the US, positive on Europe and constructive on Japan and EM, with Latin America offering diversification.
- In multi-asset, we remain mildly pro-risk, with a preference for regional diversification, selectivity and carry. In FX, we continue to favour higher-carry EM currencies, while in commodities we remain positive on gold.
Continue reading the full document
Unless otherwise stated, all information contained in this document is from Amundi Asset Management S.A.S. and is as of 14 October 2026. Diversification does not guarantee a profit or protect against a loss. The views expressed regarding market and economic trends are those of the author and not necessarily Amundi Asset Management S.A.S. and are subject to change at any time based on market and other conditions, and there can be no assurance that countries, markets or sectors will perform as expected. These views should not be relied upon as investment advice, a security recommendation, or as an indication of trading for any Amundi product. This material does not constitute an offer or solicitation to buy or sell any security, fund units or services. Investment involves risks, including market, political, liquidity and currency risks. Past performance is not a guarantee or indicative of future results.
Date of first use: 14 October 2026
Doc ID: 5992219