Convictions
Long rates are rising. Make fixed income work harder.
See how a flexible and disciplined approach to fixed income can help you navigate volatility.
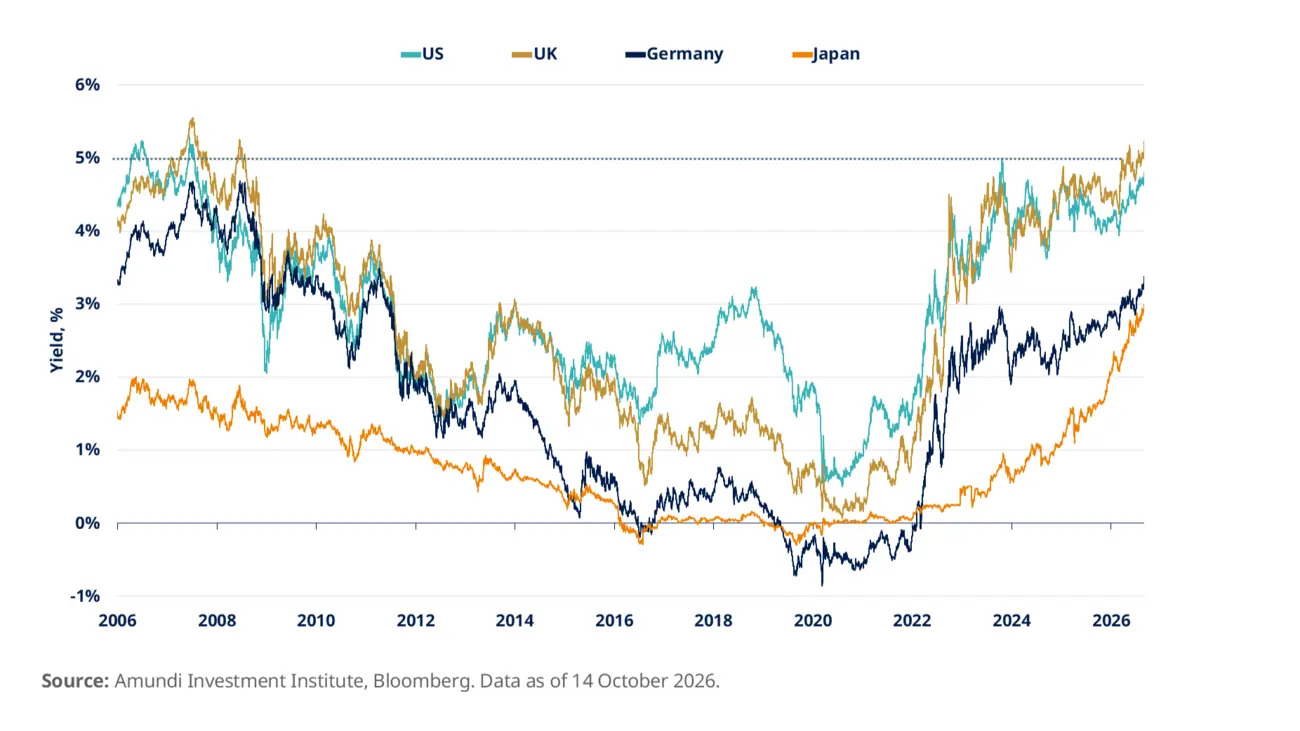
Bond yields in developed markets have risen significantly, reaching multi-year highs as investors reassess the outlook for inflation, growth, fiscal policy and central bank action.
Persistent inflationary pressures, partially driven by higher energy prices, have contributed to a repricing of interest rate expectations. At the same time, concerns about fiscal deficits and increased bond issuance, combined with investors’ demand for greater compensation for holding longer maturity debt, have placed further upward pressure on yields.
Government bond yields at multi-decade highs: 10-year Treasury yield above 5%
Central banks must maintain price stability while avoiding an economic slowdown that is more severe than necessary to return inflation sustainably towards target, particularly against a backdrop of already uneven growth. Forthcoming elections add another layer of uncertainty and could affect confidence, fiscal policy and economic decision making.
Having grown dramatically over recent decades, the bond market now offers the depth and breadth to deliver a wide dispersion of returns, driven by divergent regional growth outlooks.
Flexibility is therefore essential to tactically manage duration and yield curve positioning, helping to mitigate interest rate sensitivity as inflation, economic activity and policy expectations evolve, while also capturing opportunities as they arise. For strategies that allow active currency management, this flexibility may also extend to exploiting FX volatility.
Rising bond volatility, decoupling from equity volatility.
In a volatile environment, flexibility becomes essential
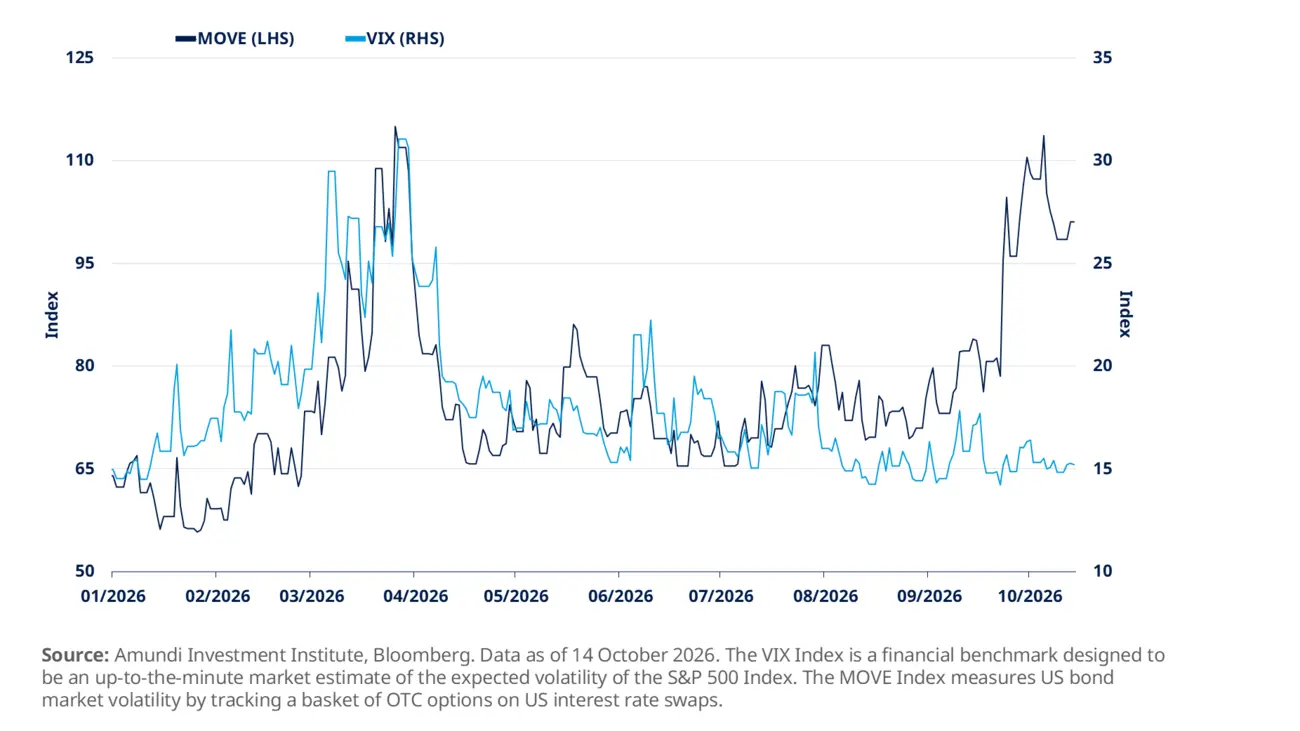
The breadth of the market creates numerous opportunities, but careful selection is essential to avoid inadvertently taking on excessive risk.
A disciplined, time-tested investment process is particularly valuable in the current environment, helping to identify issuers with sound fundamentals, resilient cash flows, and manageable refinancing needs.
Rising dispersion across US credit reinforces the need for discipline and selectivity
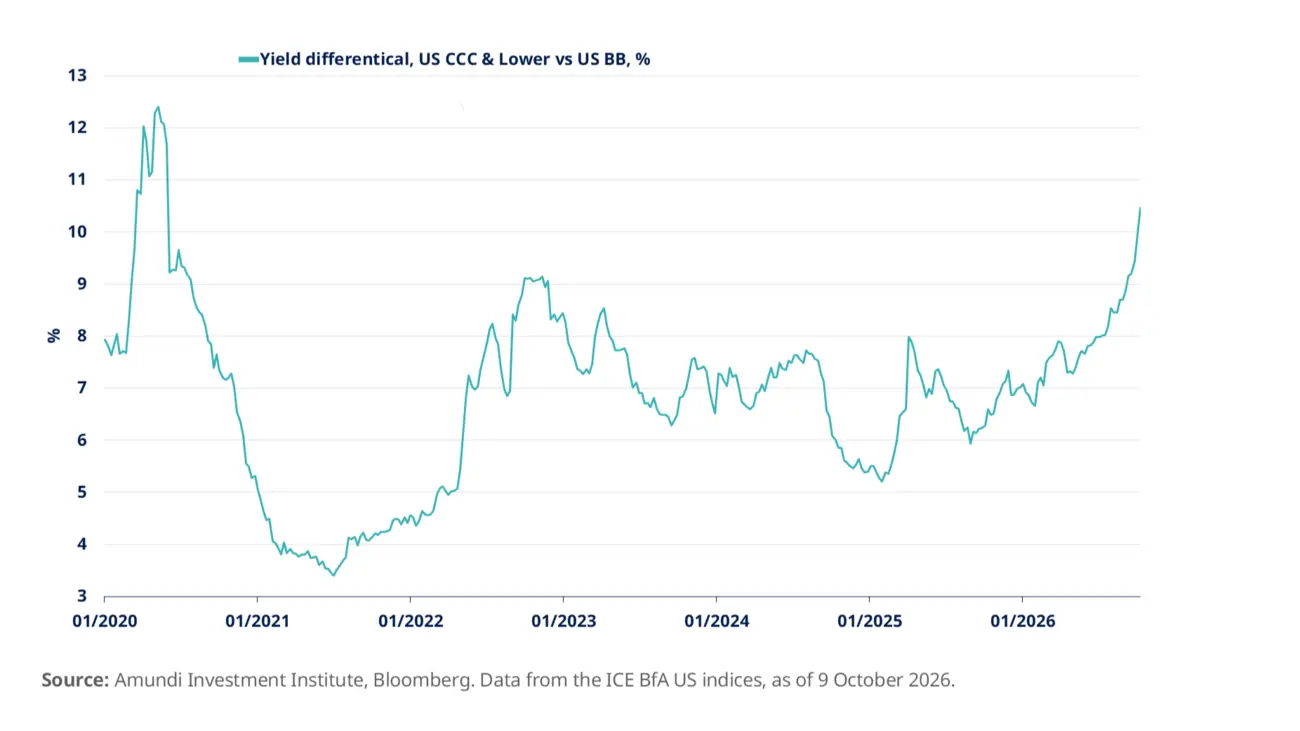
Bond yields are increasingly attractive, but volatility is likely to stay high, calling for a flexible approach to bond investing.
- 9 October 2026 -
Current starting yields have significantly improved the prospective return profile of fixed income, even within higher quality market segments. At the same time, average credit fundamentals remain solid, thanks to healthy corporate balance and adequate debt service capacity.
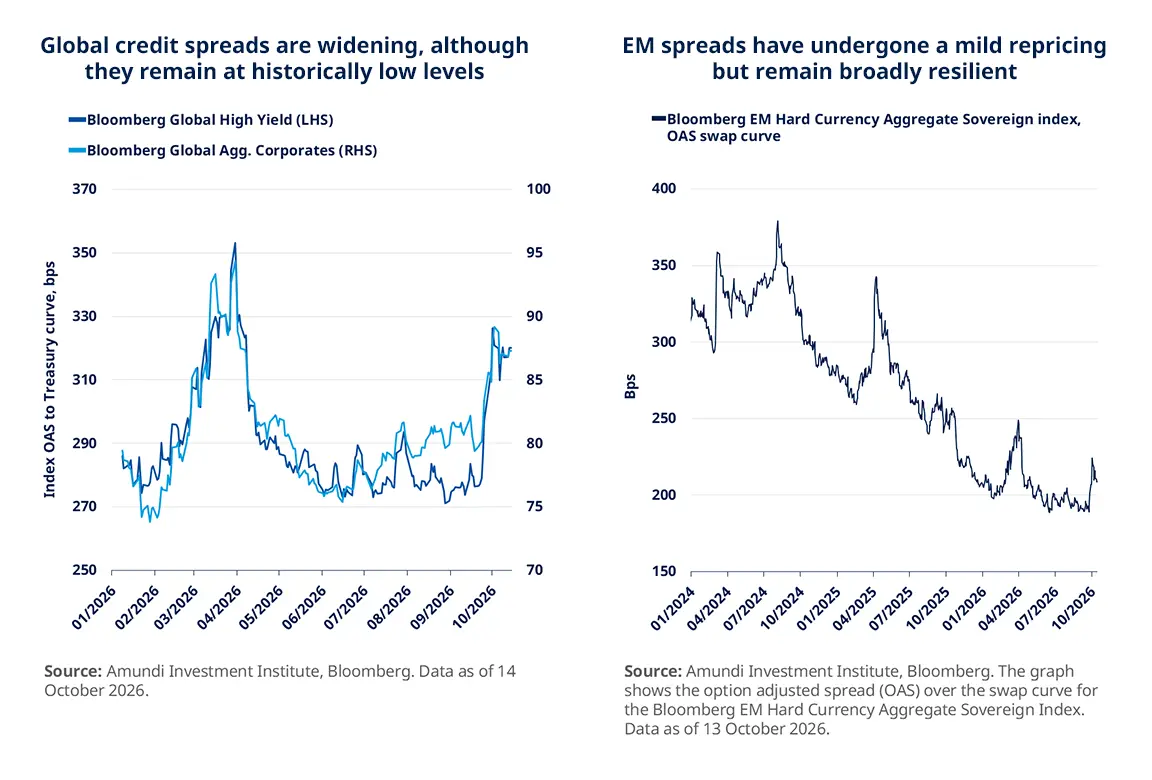
This combination provides a supportive foundation for fixed income investors. During earlier periods of exceptionally low yields, limited income left portfolios with little capacity to absorb capital losses. By contrast, today’s higher carry may provide a more substantial cushion against adverse price movements.
Persistent macroeconomic uncertainty nevertheless makes it important to look beyond yield alone. A flexible global approach can seek to benefit from these differences while reducing dependence on any single market. It may also enable portfolios to respond as relative valuations, interest rates and market conditions evolve. This includes adjusting duration as the outlook for monetary policy changes.
Taken together, these considerations support a dynamic approach. Flexibility should not, however, be confused with indiscriminate risk-taking. Careful bond selection, combined with robust and repeatable investment processes, should form the backbone of any flexible approach.
In the current environment, extensive security selection experience and the ability to adjust duration, credit and geographical exposure - without compromising liquidity or risk discipline - may be as important as the level of yield itself.
At Amundi, our well-established investment process and deep expertise enable us to capture opportunities across the broad fixed income universe, with €850 billion currently managed in active strategies as of 30 June 2026.
The team’s investment philosophy is designed to deliver consistent returns by navigating credit cycles effectively and capitalising on market inefficiencies. This agile approach combines top-down and bottom-up analysis, enabling flexible adaptation to changing market conditions.
of Active Fixed Income
Portfolio Managers
Credit Analysts
Locations in Europe and Asia
Source : Amundi as of 30 June 2026. European and Asian locations include London, Paris, Tokyo, Milan, Vienna, Munich, Barcelona, Dublin, Budapest, Singapore, Kuala Lumpur and Taipei.
* Amundi S.F. - Diversified Short Term Bond Select is the master fund of the recently launched Amundi Funds Diversified Short-Term Bond Select.
Unless otherwise stated, all information contained in this document is from Amundi Asset Management S.A.S. and is as of 15/10/2026. Diversification does not guarantee a profit or protect against a loss. The views expressed regarding market and economic trends are those of the author and not necessarily Amundi Asset Management S.A.S. and are subject to change at any time based on market and other conditions, and there can be no assurance that countries, markets or sectors will perform as expected. These views should not be relied upon as investment advice, a security recommendation, or as an indication of trading for any Amundi product. This material does not constitute an offer or solicitation to buy or sell any security, fund units or services. Investment involves risks, including market, political, liquidity and currency risks. Past performance is not a guarantee or indicative of future results.
Date of first use: 15/10/2026.
Doc ID: 6015209.