Key Takeaways
- European securitisation is regaining policy momentum as part of the European Union’s broader push to improve the efficiency of capital markets
- The proposed reforms aim to support a more efficient securitisation framework, enabling credit institutions to pool loans and convert them into securities, thereby expanding their capacity to originate new credit
- European securitisation presents attractive features for investors, including compelling spreads, low default rates, floating-rate exposure and portfolio diversification1 benefits
- Amundi’s European ABS team distinguish itself from peers, combining a long-standing market track record, broad multi-asset ABS exposure and disciplined, ESG-integrated investment expertise.
European securitisation is attracting growing interest and has moved to the centre of EU financial policy discussions in recent years. The current reform proposal, designed to review and potentially ease the capital requirements applying to banks and insurance companies, should be seen as the result of a debate shaped within the mature regulatory framework established after the global financial crisis.
Understanding securitisation in a few minutes
- What is a securitisation transaction?
- Which are the main parties involved?
- How does the securitisation process work?
- What are the benefits?
Key portfolio benefits for investors
- Attractive spreads: European securitisations can offer meaningful spread premium relative to similarly rated corporate bonds, including AAA-rated tranches which provide spreads versus swaps ranging from 40bps (prime Residential Mortgage-Backed Securities, or RMBS) up to 130bps (CLO primary)2.
- Low default rates: European securitisations, particularly senior tranches, have demonstrated low default rates over the past four decades.
- Lower interest rate sensitivity: most securitisation tranches are floating rate instruments, with coupons typically linked to short term Euribor. This naturally reduces interest rate sensitivity and helps support portfolio stability in volatile rate environments.
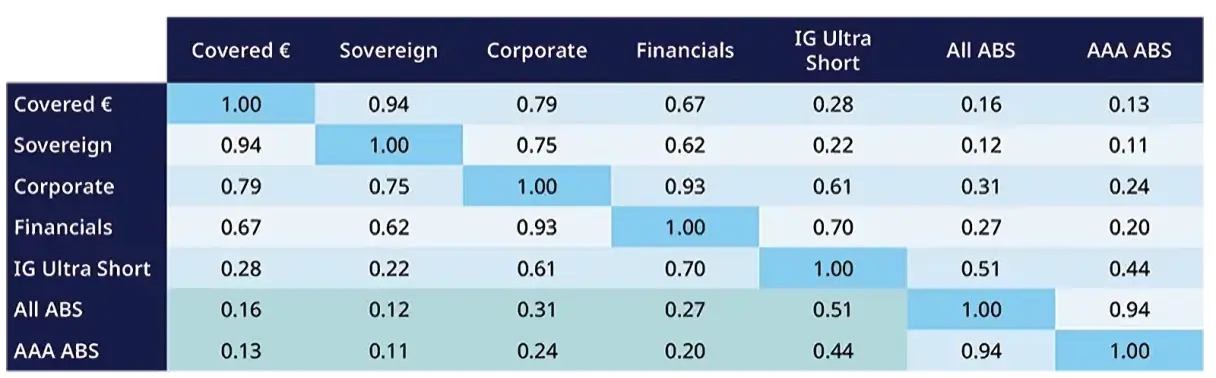
- Diversification3 beyond traditional bonds: securitisations provide exposure to assets with distinct risk drivers, helping to reduce correlation across credit segments and offering diversification beyond corporate or sovereign bond portfolios.
- Liquidity: many securitisation investors typically have long-term mandates and can tolerate price volatility. During periods of market stress, they are generally less likely to engage in forced selling and may instead act opportunistically, buying securitisations at discounted prices, which can help support overall market liquidity.
Weekly Correlation Matrix: Bloomberg ABS Index vs. iBoxx 1-3y Indices from September 2018 to September 2025
Source: Bloomberg as of end of September 2025.
Expected timeline for implementation
In October 2025, the European Commission published a Delegated Regulation4 amending Solvency II5, with the aim of easing some of the longstanding regulatory barriers that currently constrain issuance and investment, thereby supporting additional lending to households and businesses.
To achieve this, the Commission has proposed targeted amendments to several key regulations: the Securitisation Regulation, the Capital Requirements Regulation (CRR)6 and Solvency II.
As a result, the revised regulations are currently expected to enter into force in early 2027, alongside the Solvency II measures scheduled for the end of January 2027.
Expected legislative pathway from consultation to entry into force
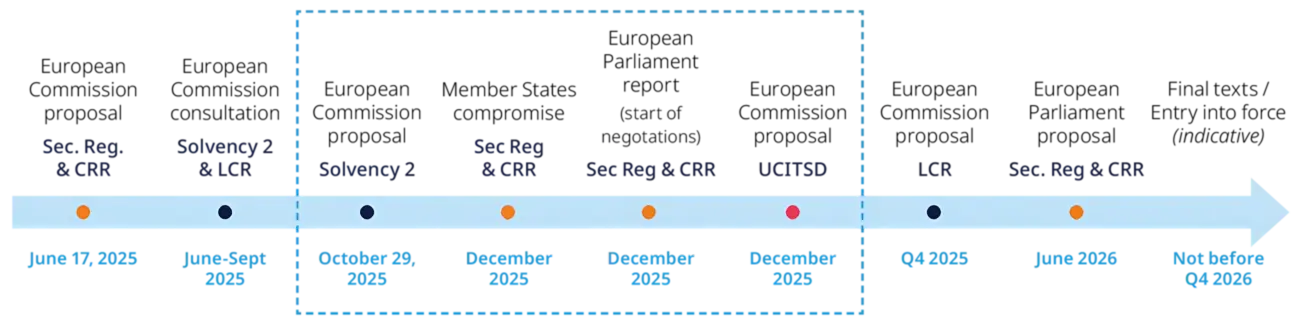
Source: Amundi. November 2025. This timeline reflects Amundi's expectations regarding the legislative pathway as of November 2025. It is provided for illustrative purposes only. Dates and steps are subject to change based on official legislative developments and do not constitute legal, financial or regulatory advice. Amundi expressly disclaims any liability for reliance on this information.
Expected impact of regulatory changes
Regardless of the exact timing of implementation, market participants may seek to increase exposure to European securitisations ahead of any potential spread compression resulting from the revised regulatory framework.
Compared with covered bonds or other secured instruments, securitisation offers an efficient way to raise capital and free up balance sheet capacity. In particular, we expect the ABS and RMBS segments to benefit from this dynamic, potentially unlocking significant issuance volumes and creating additional opportunities for capital deployment.
Why Amundi for European securitisation (ABS)
Amundi’s European ABS investment team differentiates itself from its peers through investment expertise, disciplined risk management and ESG integration7. Amundi ABS Responsible, its European open-ended ABS fund, has the longest track record in the market, having launched in 2006 and bringing more than 20 years of proven experience and expertise. The fund provides broad exposure to the European ABS universe, including RMBS, consumer credit, auto loans and CLOs.
Amundi ABS Responsible has experienced no loss related to a default since launch. Its approach is fundamental and conservative, combining top-down allocation with bottom-up selection, complemented by opportunistic investments when the risk/reward profile is attractive. The fund is characterised by continuous credit monitoring, tranche-by-tranche analysis and protection strategies designed to limit drawdowns, including CDS/iTraxx protection strategies8.
The strong investment experience of the Amundi ABS Responsible portfolio managers is further reinforced by a dedicated and experienced team of ABS analysts. ESG is also a key differentiator, with proprietary ESG scoring applied to issuers and collateral, as well as normative and sector exclusions.
Finally, Amundi is structured to meet client needs through dedicated support teams, integrated management, back-office and risk functions, and a common IT infrastructure, all supported by the company’s international presence across 35 countries. This allows Amundi to offer a high degree of customisation, responsiveness and economies of scale.
Discover our fund
Amundi ABS Responsible
Read our news and insights

Read the full article
[1] Diversification does not guarantee a profit or protect against a loss.
[2] Association for Financial Markets in Europe, AFME Q2 2025 Securitisation Report, 30 September 2025
[3] Diversification does not guarantee a profit or protect against a loss.
[4] A delegated regulation is an EU legal act used to supplement or amend non-essential parts of an existing EU law, without reopening the full legislative process.
[5] Directive (EU) 2009/138/EG “Solvency II” has formed the prudential framework for insurers across the European Union since 2016.
[6] The Capital Requirements Regulation (CRR) covers the prudential framework for credit institutions. The main changes focus on the regulatory capital calculation rules for securitization exposures.
[7] There is no guarantee that ESG considerations will improve the strategy or performance of the sub-fund. Please refer to Amundi's Responsible Investment Policy and Amundi's Sustainable Finance Disclosure Statement.
[8] Hedging strategies implemented through credit default swaps (CDS) and/or iTraxx indices, designed to reduce portfolio credit risk and limit potential drawdowns.
Unless otherwise stated, all information contained in this document is from Amundi Asset Management S.A.S. and is as of 01/09/2026. Diversification does not guarantee a profit or protect against a loss. The views expressed regarding market and economic trends are those of the author and not necessarily Amundi Asset Management S.A.S. and are subject to change at any time based on market and other conditions, and there can be no assurance that countries, markets or sectors will perform as expected. These views should not be relied upon as investment advice, a security recommendation, or as an indication of trading for any Amundi product. This material does not constitute an offer or solicitation to buy or sell any security, fund units or services. Investment involves risks, including market, political, liquidity and currency risks. Past performance is not a guarantee or indicative of future results.
Date of first use: 01/09/2026
Doc ID: 5806031